How Long Does It Take to Buy a House in Utah?
You've decided you're ready to buy a house.
Great.
So when do you get the keys?
Next month?
Three months from now?
Six months?
The frustrating answer is that there isn't one exact timeline for buying a home.
Some buyers find the right property almost immediately. Others search for months before making an offer. And even after you're under contract, there are inspections, financing, appraisal, title work and closing to complete.
If you're planning to buy a home in Utah, understanding the general process can help you figure out when you should actually get started.
Start Before You're Ready to Tour Homes
Your home buying process should ideally begin before you start scheduling showings.
If you're financing the purchase, one of your first conversations should be with a lender.
They can help you understand your buying power, estimated cash requirements and potential loan options.
This also gives you time to identify financial issues that may need attention before you're ready to make an offer.
You don't want to find the perfect house on Saturday and discover on Monday that you aren't financially prepared to buy it.
Preapproval Can Be Pretty Quick
Depending on your financial situation and how quickly you provide documentation, the preapproval process may move relatively quickly.
Your lender may request information about your income, assets, debts, employment and credit.
If your financial situation is more complicated, it could take additional time.
The important thing is to start early enough that you aren't rushing when the right property comes along.
Then Comes the House Hunt
This is the part of the timeline that varies the most.
You might find your house during your first weekend of showings.
You might look for three months.
You might make several offers before one is accepted.
Your timeline can depend on your budget, location, needs, inventory and market competition.
If your search criteria are extremely specific, expect the search to potentially take longer.
Your Wish List Affects Your Timeline
Imagine you're looking for:
Four bedrooms.
Three bathrooms.
At least half an acre.
A three car garage.
A finished basement.
Mountain views.
A specific school boundary.
And you don't want to spend more than $450,000.
The more requirements you add, the smaller your pool of potential homes becomes.
There's nothing wrong with having priorities.
But separate your must haves from your nice to haves.
That can make your search much more productive.
Finding the House Doesn't Mean You Get It
You finally find the one.
Now we write an offer.
But the seller still has to accept it.
If you're competing with other buyers, you may not win the first property you offer on.
That can add days, weeks or even months to your overall timeline.
This is one reason it's difficult to predict exactly when someone will buy a home before they start shopping.
Once Your Offer Is Accepted, the Clock Changes
After you're under contract, the process becomes much more structured.
Now we have contractual deadlines.
Earnest money.
Due diligence.
Financing and appraisal conditions.
Settlement.
Closing related obligations.
Your specific contract determines the actual dates, but now we have a roadmap toward closing.
Earnest Money Comes Early
Once you're under contract, you'll need to deliver your earnest money according to the terms and deadline in your purchase agreement.
This usually happens early in the transaction.
Know the amount, where it needs to go and when it's due.
Don't let an avoidable missed deadline create problems right at the beginning.
Due Diligence Happens Next
Your due diligence period gives you time to investigate the property according to your contract.
This is when buyers commonly schedule a professional home inspection.
Depending on the property, you may also investigate other concerns such as sewer, radon, structural issues or other systems.
Schedule inspections quickly.
If you wait too long, you may not have enough time to investigate additional concerns before your contractual deadline.
Your Lender Is Working at the Same Time
While you're inspecting the house, your lender is continuing the loan process.
They may ask for updated financial documents.
Send them quickly.
Mortgage transactions involve a lot of moving pieces and delays in documentation can slow things down.
Your lender may also coordinate the appraisal if one is required.
The Appraisal Can Affect Timing
The appraisal doesn't necessarily happen the day after your offer is accepted.
It needs to be ordered, scheduled, completed and reviewed.
Timing can vary depending on availability and the property.
If the appraisal comes in as expected, great.
If there's an issue, such as a lower than expected value, the parties may need additional time to determine what happens next.
Title Work Happens Behind the Scenes
The title company is also working during this period.
They're researching the property and preparing for the transfer of ownership.
If everything is straightforward, this may happen without you noticing much.
If a title issue appears, it may need to be resolved before closing.
Some issues can be addressed quickly.
Others can affect the timeline.
Homeowners Insurance Needs to Be Arranged
If you're financing the home, your lender may require homeowners insurance.
Start shopping before the last minute.
You need time to compare coverage and cost.
If the property presents an insurance issue, discovering it early gives you more time to explore your options.
Underwriting Can Feel Quiet
There may be a period during the transaction where it feels like nothing is happening.
A lot is happening.
Your lender is reviewing documents.
The title company is working.
The appraisal may be processing.
Conditions are being cleared.
Your loan may be moving through underwriting.
This is the behind the scenes part of buying a house.
Don't mistake silence for inactivity.
Underwriting May Ask for More Documents
It's common for buyers to receive additional requests during underwriting.
Maybe the lender needs an updated bank statement.
Maybe they need clarification about a deposit.
Maybe they need another employment document.
This doesn't automatically mean your loan is in trouble.
Respond quickly and keep the process moving.
Don't Create Your Own Delay
While you're waiting, don't make major financial changes without talking to your lender.
Don't finance a new vehicle.
Don't open a bunch of new credit cards.
Don't make unexplained financial moves.
Don't change jobs without communicating.
The lender is working toward approving the financial situation they reviewed.
Changing that situation can create additional work or potentially affect your financing.
Then Comes the Final Walkthrough
As closing approaches, you'll typically complete a final walkthrough.
This isn't another full inspection.
You're checking that the property is generally in the expected condition, included items remain and agreed upon repairs have been addressed.
If something significant is wrong, we want to know before closing.
Settlement and Signing
Eventually, it's time to sign.
You'll review and sign the required closing documents.
If you're financing, expect a decent amount of paperwork.
But don't assume signing means you're immediately getting the keys.
There may still be funding and recording steps before the transaction is complete.
Recording and Possession Matter
In Utah, the transaction isn't necessarily complete simply because you finished signing documents.
Applicable documents still need to be handled and recorded as required.
Your purchase contract also determines when you're entitled to possession.
That means you shouldn't schedule your moving truck based solely on the time of your signing appointment.
Know when possession actually occurs.
So How Long Does It Actually Take?
If you already have an accepted offer, your contract provides the most useful answer.
The settlement and closing dates you've agreed to will determine the expected timeline.
If you haven't started shopping yet, the timeline is much harder to predict.
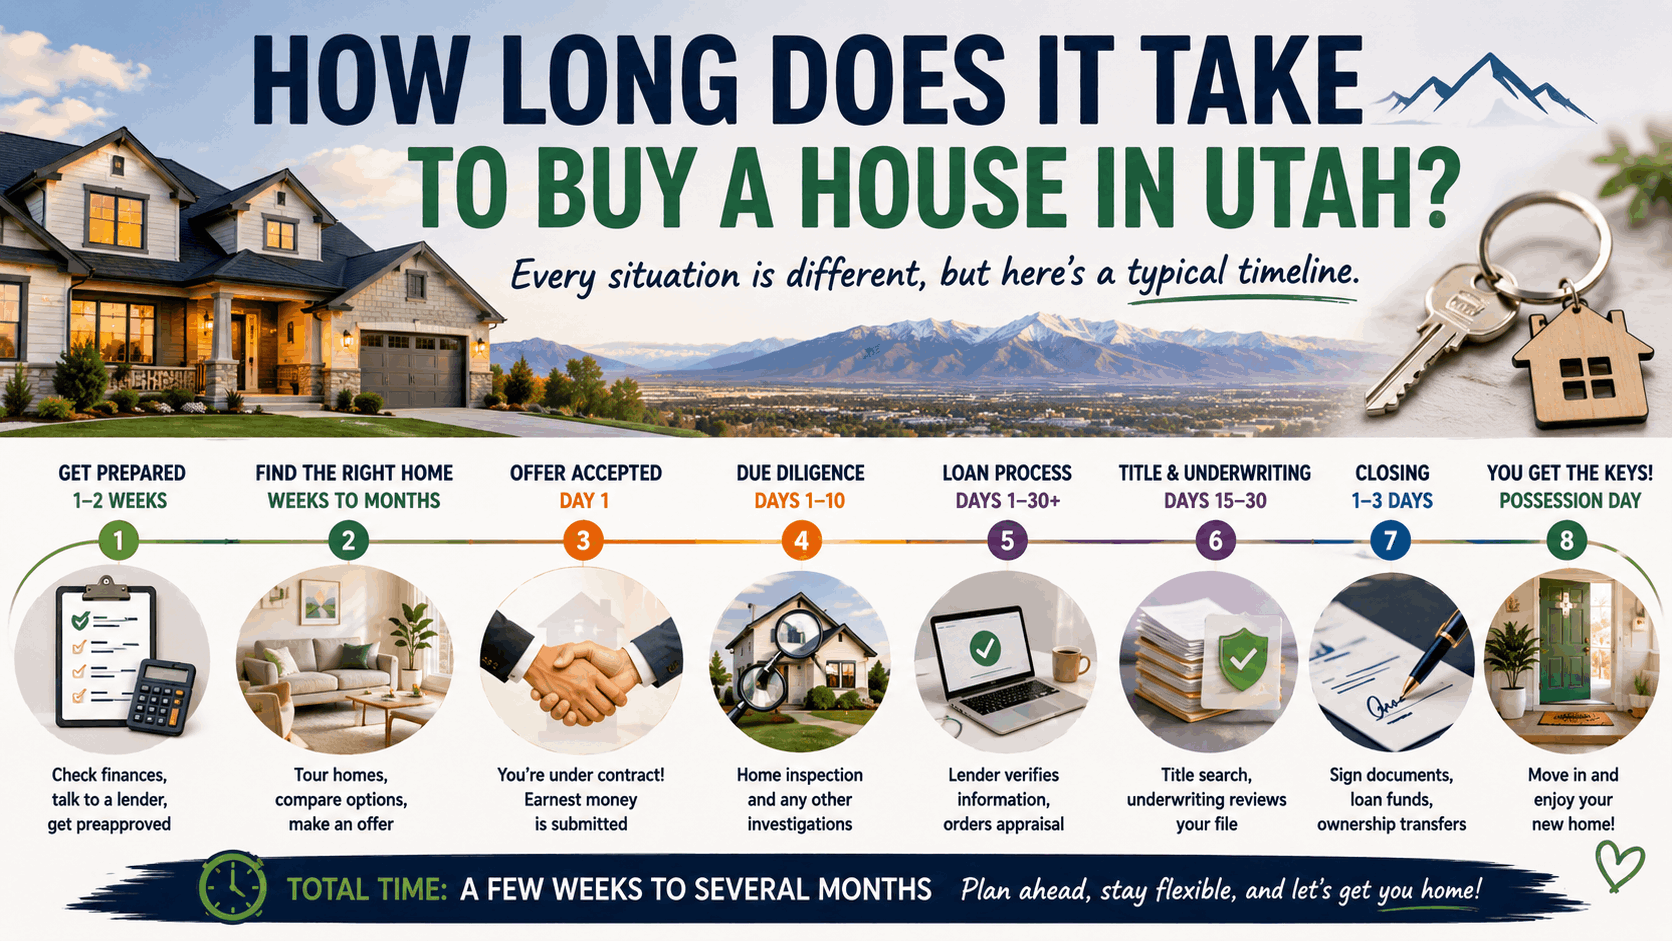
You need time for:
Getting financially prepared.
Getting preapproved.
Finding the property.
Negotiating an accepted offer.
Completing due diligence.
Completing financing.
Appraisal.
Title work.
Closing.
The actual home search might take a weekend or several months.
That's why buyers with a specific move date should start the process earlier than they think they need to.
When Should You Start If You Want to Move by a Certain Date?
If you know you want to be in a home by summer, don't wait until summer to call your lender.
Start the conversation months beforehand.
That doesn't mean you need to immediately make an offer.
It gives you time to understand your finances, improve anything that needs attention and learn the market before you're under pressure.
Starting early gives you options.
Starting late gives you deadlines.
Renters Should Think About Their Lease
If you're currently renting, review your lease before buying.
When does it end?
How much notice do you need to provide?
What happens if you leave early?
Would you rather have a small overlap between your lease and homeownership than risk having nowhere to live if closing gets delayed?
Don't assume the dates will line up perfectly.
A little flexibility can make moving much less stressful.
Sellers Who Are Also Buying Need Extra Planning
If you're selling one home and buying another, your timeline becomes more complicated.
Now we may need to coordinate two transactions.
Your sale.
Your purchase.
Financing.
Possession.
Moving.
Potential contingencies.
This is where planning ahead becomes especially important.
We want to think through how the transactions work together before you're surrounded by moving boxes.
Delays Can Happen
Even well managed transactions can encounter delays.
An appraisal takes longer than expected.
The lender needs additional documentation.
A title issue appears.
A repair isn't finished.
The parties agree to adjust a deadline.
Not every delay is a disaster.
But having some flexibility in your moving plans can save you a lot of stress.
Don't Plan Everything Around the Earliest Possible Date
If your contract anticipates closing on a particular date, don't assume you'll be unloading the moving truck at 8:00 that morning.
Know when possession occurs.
Build some breathing room into your plans where possible.
Especially if you're coordinating movers, utilities, time off work or the end of a lease.
Start Earlier Than You Think
You don't have to be ready to buy tomorrow to start preparing today.
Talking with a lender and real estate agent early doesn't obligate you to purchase a house.
It gives you information.
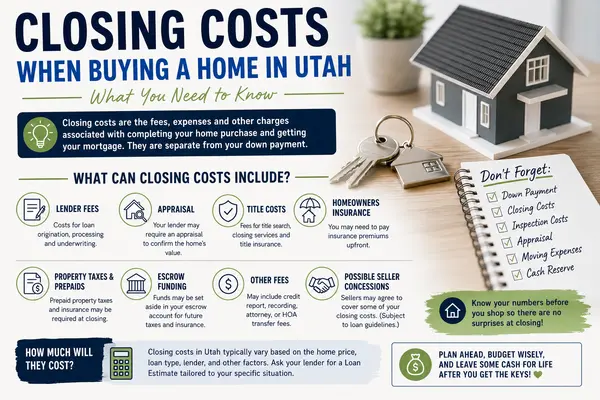
You'll know what you can afford.
You'll understand what cash you may need.
You'll see what's available in your target areas.
And when you're actually ready to buy, you'll already understand the process.
If you're hoping to buy a home in Northern Utah or anywhere along the Wasatch Front, don't wait until the month you need to move to start figuring everything out.
Give yourself time.
The right house might show up immediately.
Or it might take a while.
Either way, being prepared means you'll be ready when it does.
Categories
Recent Posts