What Happens If Your Home Appraises for More Than You Offered?
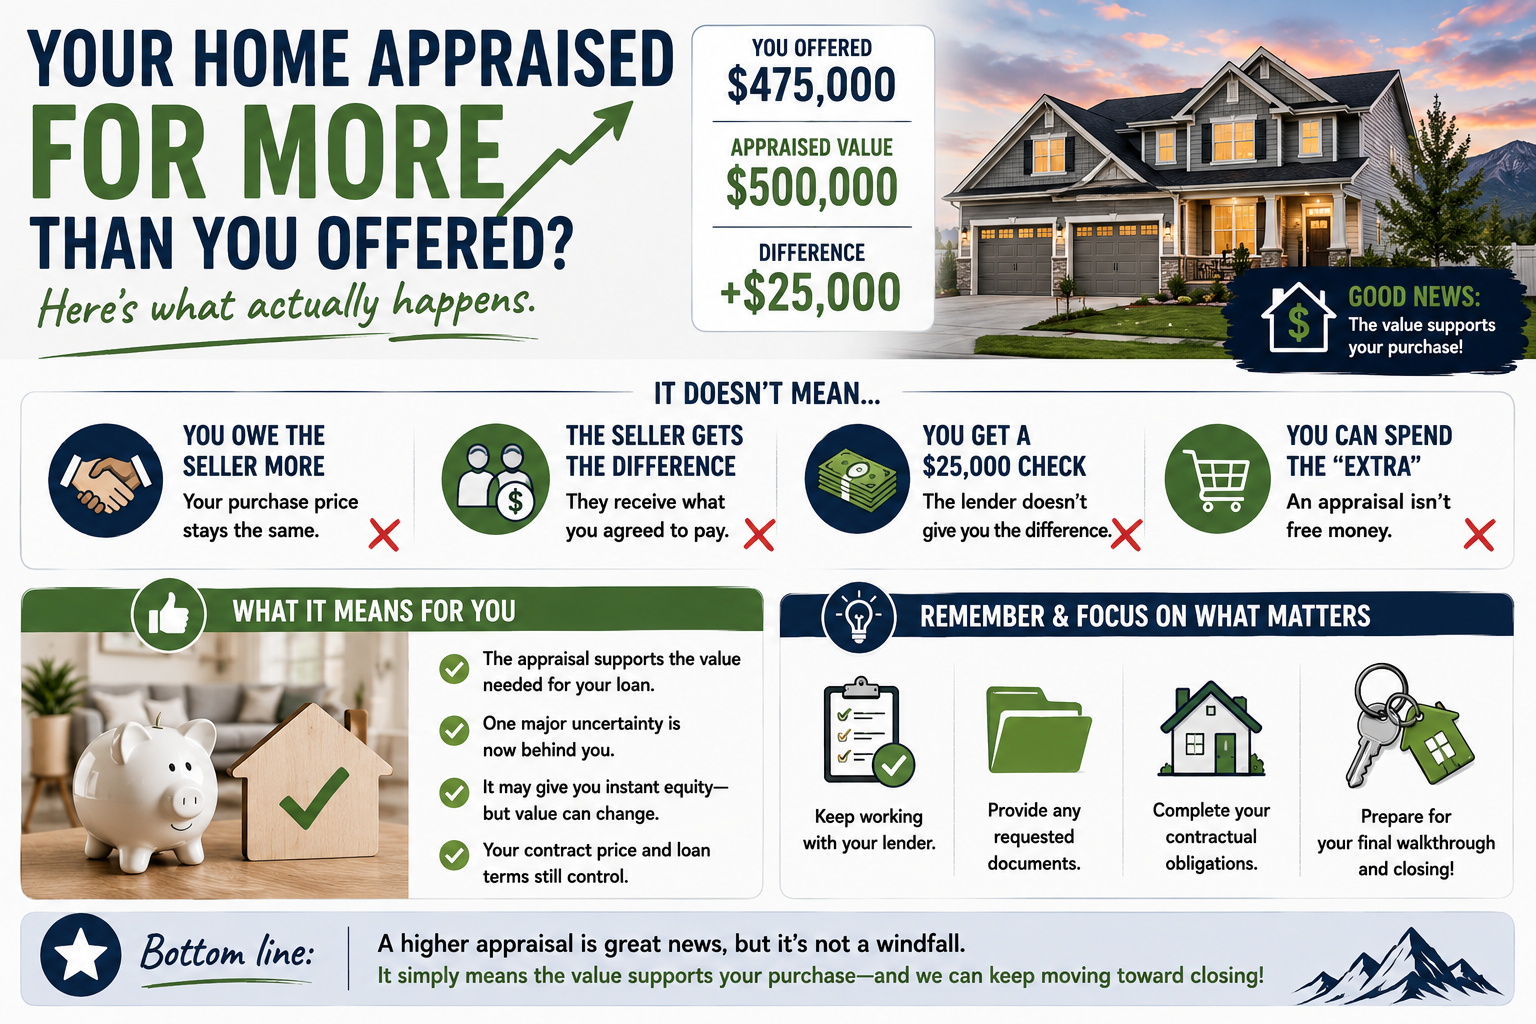
You offered $475,000 on a home.
The seller accepted.
Then the appraisal comes back at $500,000.
So... what happens to that extra $25,000?
Do you owe the seller more money?
Does your lender give you the difference?
Did you just instantly make $25,000?
A home appraising for more than your purchase price is generally good news for a buyer, but it doesn't mean a pile of extra cash suddenly appears at closing.
Here's what it actually means.
First, What Is an Appraisal?
An appraisal is an independent opinion of a property's value completed by a licensed or certified appraiser.
When you're financing a home, your lender may require an appraisal as part of the loan process.
The lender wants to understand the value of the property being used as collateral for the mortgage.
The appraiser may consider factors such as the property itself, its condition, location and comparable sales.
The appraisal isn't the same thing as your home inspection.
The inspector is primarily evaluating the property's condition.
The appraiser is developing an opinion of value.
Your Purchase Price Doesn't Automatically Change
Let's use our original example.
You agree to buy the home for $475,000.
The appraisal comes back at $500,000.
You generally don't suddenly owe the seller $500,000.
Your purchase price remains governed by your contract.
The seller agreed to sell at the negotiated price.
A higher appraisal doesn't automatically rewrite that agreement.
The Seller Doesn't Get the Difference
The seller also doesn't automatically receive an extra $25,000 just because the appraisal came in higher.
The purchase price is what the parties agreed to in the contract unless they later agree to modify it.
That's one reason sellers care so much about pricing and negotiations before accepting an offer.
Once a contract is in place, an appraisal doesn't simply reset the sales price to the appraised value.
You Don't Get a $25,000 Check Either
This is where buyers sometimes get excited.
If the appraisal says $500,000 and you're paying $475,000, the lender doesn't generally hand you $25,000 at closing.
The appraisal isn't a coupon.
It's an opinion of value used as part of the lending process.
You still purchase the property according to the terms of your contract and loan.
Does That Mean You Have $25,000 in Equity?
Potentially, you could think of the difference between the appraised value and purchase price as a form of initial equity.
But be careful with that word.
An appraisal is an opinion of value at a particular point in time.
It doesn't guarantee that you could immediately sell the property for that exact amount.
Market conditions can change.
Another appraiser could reach a different conclusion.
Selling a home also involves transaction costs.
So yes, a higher appraisal can be encouraging.
But don't mentally spend that equity before you've even moved in.
Why Is a Higher Appraisal Good News?
Because one of the uncertainties in a financed transaction may have just become less concerning.
When the appraisal supports at least the value needed for the transaction, the lender can generally continue evaluating the loan without a low appraisal creating an additional valuation issue.
That doesn't mean your loan is automatically approved.
The lender still needs to complete underwriting and satisfy its other requirements.
But from an appraisal standpoint, a value above the contract price is usually much easier to deal with than one below it.
Does a Higher Appraisal Lower Your Down Payment?
Not necessarily.
This is a common misunderstanding.
Suppose you're planning to make a particular percentage down payment.
You may think:
"If the house appraised higher, can't I use that extra value instead of bringing as much money?"
For a purchase transaction, lenders generally calculate the loan based on applicable lending guidelines, which commonly consider the lower of the purchase price or appraised value.
The exact rules depend on your loan.
Don't change your cash to close assumptions based solely on a higher appraisal.
Ask your lender how the appraisal affects your specific financing.
Does It Remove Mortgage Insurance?
Not automatically.
If your loan includes mortgage insurance, a higher appraisal at the time of purchase doesn't necessarily mean it immediately disappears.
Mortgage insurance requirements depend on your loan program and financing structure.
If you're wondering whether a higher appraisal changes anything about mortgage insurance, ask your lender to run the actual numbers.
Does the Seller See the Appraisal?
Not necessarily.
The appraisal is generally obtained as part of the buyer's financing process.
Who receives it and whether it is shared can depend on the transaction and circumstances.
If the appraisal comes in higher than the contract price, there usually isn't a reason to panic that the seller will automatically increase the price.
Again, the existing contract controls the agreed purchase price unless the parties modify it.
Can the Seller Cancel Because It Appraised Higher?
A higher appraisal by itself generally doesn't give a seller an automatic right to cancel an otherwise binding purchase agreement simply because they now wish they had negotiated a higher price.
The parties' rights depend on the actual contract.
If a seller has questions about their obligations, they should review the agreement with their real estate professional and obtain legal advice when appropriate.
What If You Offered Above Asking Price?
This can make the higher appraisal feel especially satisfying.
Maybe the home was listed at $450,000.
You offered $475,000 because there was competition.
You were worried you'd gone too high.
Then the appraisal comes back at $485,000.
That can provide some reassurance that the appraiser's opinion of value supports the price you agreed to pay.
It doesn't guarantee the investment will appreciate.
But it may help ease the concern that you dramatically overpaid based on the appraisal.
What If the Appraisal Is Exactly the Purchase Price?
That's common too.
If you agree to pay $475,000 and the appraisal comes in at $475,000, the value supports the contract price for purposes of that appraisal.
There's no bonus for coming in higher.
The important thing is whether the appraisal supports what is needed for the transaction.
The Bigger Concern Is Usually a Low Appraisal
Buyers tend to worry much more when the appraisal comes in below the purchase price.
If you agreed to pay $475,000 and the appraisal comes in at $450,000, now there may be a valuation gap that needs to be addressed.
What happens next depends on your financing and the terms of your purchase contract.
Potential options might include negotiations between the parties, additional buyer funds where appropriate or other steps depending on the circumstances.
That's why appraisal terms matter when we write the offer.
A Higher Appraisal Doesn't Mean You Got a Guaranteed Deal
It's tempting to think:
"I bought a $500,000 house for $475,000, so I made $25,000 today."
Maybe.
But real estate value isn't quite that simple.
The appraisal is one professional opinion.
The true market value of the property is ultimately influenced by what buyers are willing to pay under current conditions.
If you immediately put the home back on the market, there's no guarantee another buyer would pay exactly $500,000.
Your Equity Changes Over Time
After you buy the home, your equity can change for several reasons.
You pay down your mortgage.
Property values may rise or fall.
You may improve the home.
The local market may change.
Your starting position matters, but homeownership is usually a longer term financial picture.
A strong appraisal is encouraging.
It isn't a promise about future value.
Don't Change Your Plans Just Because the Number Is Higher
If the appraisal comes in above the purchase price, great.
Celebrate the good news.
Then keep doing exactly what your lender tells you to do.
Don't go finance furniture.
Don't open a new credit card because you suddenly feel wealthier.
Don't start spending money based on equity you haven't actually accessed.
You're still in the middle of a mortgage transaction.
Get to closing first.
What Should You Do After a High Appraisal?
Usually, not much.
Continue working with your lender.
Keep providing requested documents.
Maintain your financial situation.
Complete the rest of your contractual obligations.
Prepare for your final walkthrough and closing.
A high appraisal is one of those moments in a real estate transaction where no additional problem to solve is a very good thing.
What Does It Mean for Sellers?
If you're selling and the appraisal supports a value higher than your contract price, it's understandable to wonder whether you left money on the table.
Maybe.
Maybe not.
An appraisal isn't the same thing as having another buyer willing to pay that amount under the same terms.
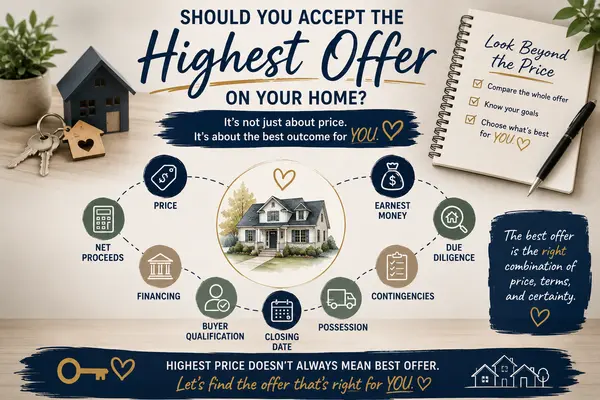
When you accepted the offer, you were evaluating the actual buyer, price, financing, contingencies, timeline and market conditions available at that time.
The goal isn't to predict the highest theoretical number anyone could ever assign to the property.
It's to negotiate a strong transaction that successfully closes.
Price, Appraised Value and Market Value Aren't Always Identical
These three numbers can be different.
The list price is what the seller chooses to ask.
The purchase price is what the buyer and seller agree to.
The appraised value is the appraiser's opinion of value.
And the broader market is constantly changing based on actual buyer and seller behavior.
Understanding those differences can make the appraisal process much less confusing.
The Best Appraisal Is Usually an Uneventful One
For most buyers, the goal isn't necessarily to get an appraisal that's dramatically higher than the purchase price.
The goal is to have an appraisal that supports the transaction so you can keep moving toward closing.
If it comes in higher?
Great.
If it supports the purchase price?
Great.
Either way, we're one step closer to getting the keys.
If you're buying a home in Northern Utah or anywhere along the Wasatch Front, understanding how appraisal terms fit into your offer before you submit it can save you a lot of confusion later.
Because the appraisal shouldn't be the first time you start thinking about value.
Categories
Recent Posts