What Does a Title Company Do When You Buy a House in Utah?
When you buy a home, there are a lot of people involved in getting you from an accepted offer to closing day.
Your real estate agent.
Your lender.
Your inspector.
Your appraiser.
And then there's the title company.
For many buyers, the title company is one of the least understood parts of the transaction. You may not hear from them as often as your agent or lender, but they're doing important work behind the scenes before ownership of the property transfers to you.
So what exactly does a title company do when you buy a house in Utah?
Let's break it down.
What Is a Title Company?
A title company helps facilitate the transfer of real estate from one owner to another.
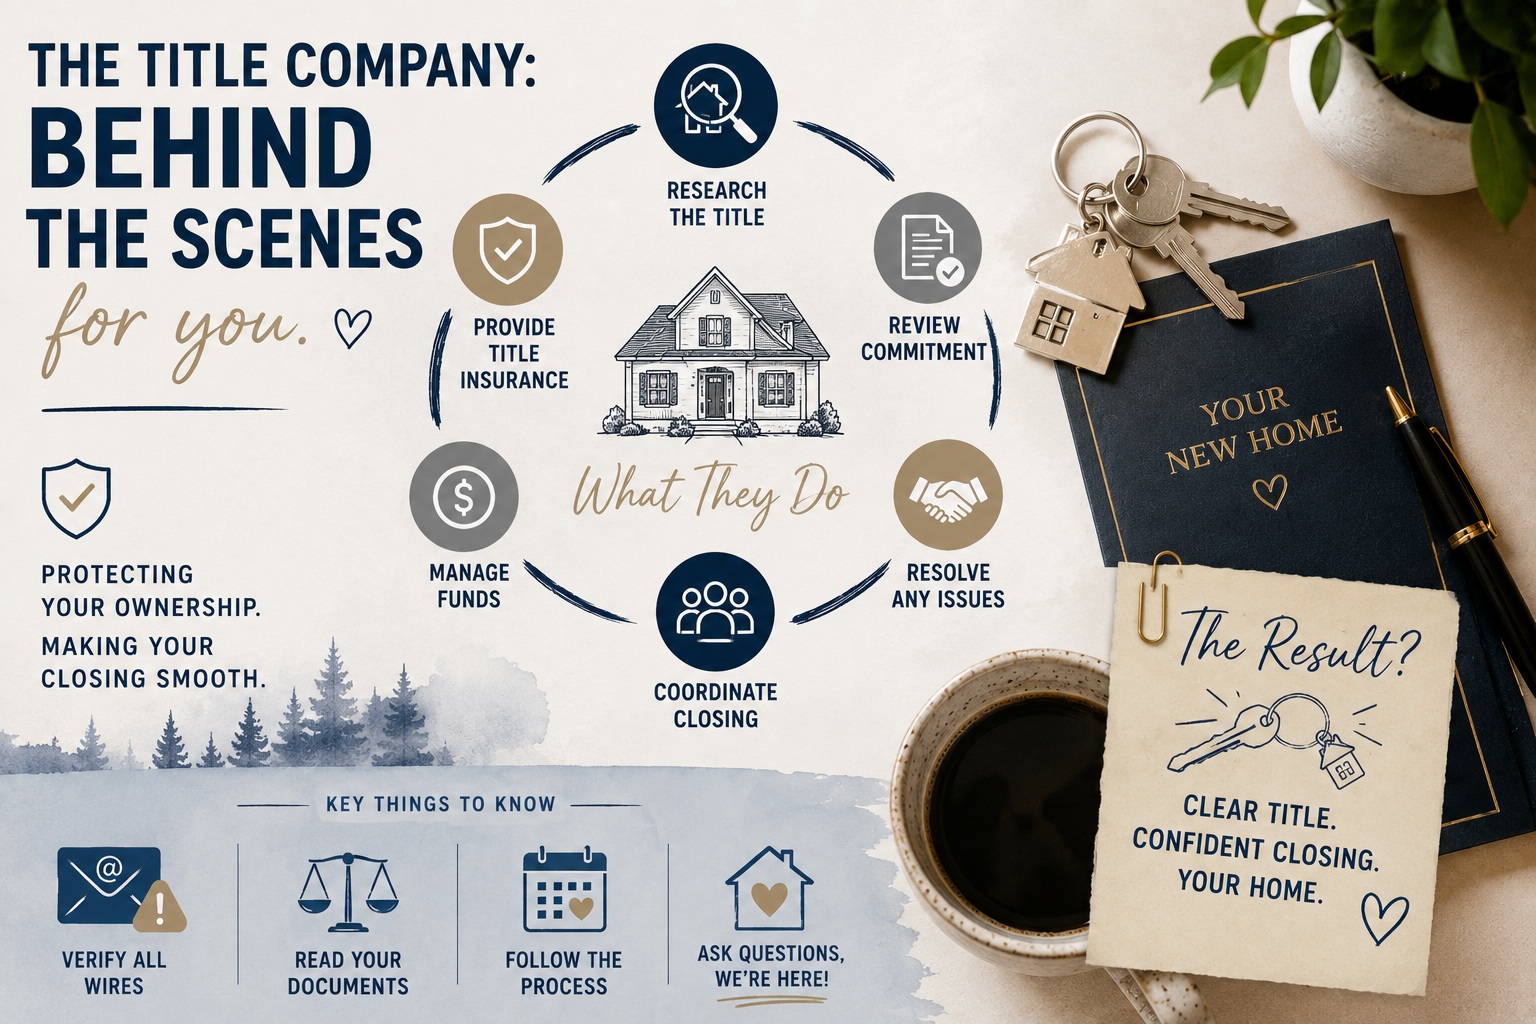
One of its primary responsibilities is researching the property's title and helping identify certain issues that could affect ownership.
The title company may also coordinate documents, funds, closing and recording depending on its role in the transaction.
Essentially, they're helping make sure the ownership side of your home purchase is ready for closing.
What Does "Title" Mean?
When we talk about title in real estate, we're talking about legal ownership rights to the property.
A deed is a document used to transfer an interest in real property.
Title refers more broadly to the ownership rights themselves.
Before you purchase a home, you want to understand whether there are matters affecting the property's title that need to be addressed.
That's where the title process becomes important.
The Title Search
After you're under contract, the title company researches available public records and other relevant information regarding the property.
The goal is to identify matters that could affect title.
Depending on the property, the search may reveal things such as:
- Existing mortgages
- Certain liens
- Judgments affecting an owner
- Easements
- Property restrictions
- Recorded agreements
- Ownership issues
- Other recorded matters
Not everything discovered is necessarily a problem.
Some items are normal and remain associated with the property.
Others may need to be resolved before ownership can transfer as intended.
What Is a Title Commitment?
During the transaction, you may receive a title commitment.
This is an important document, and it's worth reviewing.
A title commitment generally describes the conditions under which a title insurance policy will be issued and identifies certain exceptions or requirements related to the property.
In plain English, it can help show what the title company found and what will or won't be covered by the proposed title insurance policy.
If you don't understand something listed in the commitment, ask questions.
Your real estate professional and title company can help explain the transaction, while legal questions should be directed to a qualified attorney.
What Happens to the Seller's Mortgage?
Many sellers still have a mortgage when they sell their home.
That's normal.
As part of preparing for closing, the appropriate payoff information is obtained so the existing loan can be paid from the seller's proceeds according to the transaction.
The goal is for the buyer to receive the ownership interest contemplated by the contract without unexpectedly taking on the seller's mortgage.
What About Liens?
A title search may reveal liens or other claims affecting the property.
Some may need to be paid or otherwise addressed as part of the closing process.
For example, there could potentially be issues involving unpaid obligations that resulted in recorded liens.
How a particular issue is handled depends on the nature of the lien and the transaction.
The important thing is identifying these matters before closing rather than discovering them after you've purchased the home.
What Is Title Insurance?
Title insurance is different from homeowners insurance.
Homeowners insurance generally protects against certain future events involving the property, such as covered damage or losses.
Title insurance relates to certain covered title issues.
There are different types of title insurance policies, including policies that protect lenders and policies that protect owners.
The exact coverage depends on the policy, including its terms, exclusions and exceptions.
What Is Lender's Title Insurance?
If you're obtaining a mortgage, your lender may require a lender's title insurance policy.
This policy protects the lender's interest according to the terms of the policy.
It does not provide the same protection to you as an owner's policy.
That's an important distinction.
What Is Owner's Title Insurance?
An owner's title insurance policy is intended to protect the homeowner against certain covered title issues according to the policy terms.
Title problems aren't always obvious.
There could potentially be issues involving past ownership, recording errors, undisclosed interests or other matters.
Your title company can explain the specific coverage being offered, including exclusions and exceptions.
The Title Company Helps Prepare for Closing
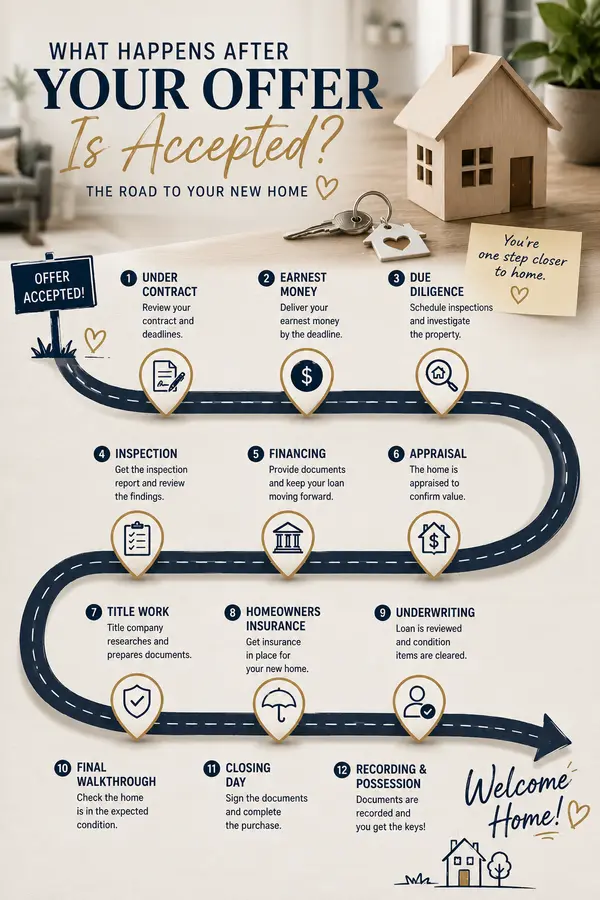
As closing approaches, the title company works with the parties and other professionals involved in the transaction.
That may include coordinating with:
- The buyer
- The seller
- Real estate agents
- Lenders
- Other parties involved in the transaction
There are a lot of numbers and documents that need to line up before ownership can transfer.
The title company plays an important role in coordinating that process.
What Happens to the Money at Closing?
Real estate transactions involve a lot of money moving between different parties.
Depending on the transaction, funds may include:
- The buyer's funds
- Mortgage proceeds
- Seller proceeds
- Existing mortgage payoffs
- Certain closing expenses
- Taxes or prorations
- Other transaction related amounts
The settlement process accounts for the money according to the closing documents and transaction requirements.
This is one reason buyers should always follow verified wiring instructions and be extremely cautious about wire fraud.
Wire Fraud Is a Serious Risk
This deserves its own section.
Real estate transactions can be targeted by scammers attempting to send fake wiring instructions.
Never assume an email containing new or changed wiring instructions is legitimate.
Before sending funds, verify the instructions directly with your title company using trusted contact information.
Don't rely solely on contact information contained in an unexpected email.
If something changes at the last minute, stop and verify it.
A few minutes of caution can protect a very large amount of money.
What Happens on Closing Day?
At closing, you'll sign the documents required for your purchase.
If you're financing the home, that will generally include mortgage related documents as well.
The title or settlement company helps facilitate the signing and settlement process according to the transaction.
But signing documents doesn't necessarily mean you're immediately the legal owner.
There are still final steps to complete.
What Does Recording Mean?
Real estate documents related to the transfer are recorded with the appropriate county recorder.
Recording places the relevant documents into the public record.
The timing of possession and when you receive keys depends on the terms of your contract and transaction, so don't assume signing automatically means you can immediately move in.
Your agent and title company can help you understand what happens next.
Why Does the Title Company Need Information From Me?
During the transaction, the title company may request information needed to prepare for closing.
Respond promptly and make sure you're communicating through legitimate channels.
If you're ever unsure whether a request actually came from the title company, call them using a verified phone number.
Again, wire fraud and impersonation attempts are real.
It's worth being cautious.
Should Buyers Actually Read the Title Documents?
Yes.
Real estate comes with paperwork, and some of it isn't particularly exciting.
Read it anyway.
Pay attention to the title commitment and the exceptions affecting the property.
If you see something you don't understand, ask.
Maybe there's an easement.
Maybe there are recorded restrictions.
Maybe there's an issue that needs additional investigation.
You want to understand what you're buying before you own it.
Title Work Is One of the Quiet Parts of Buying a Home
When everything goes smoothly, buyers may barely notice how much work happens behind the scenes.
That's usually a good thing.
The title company is helping research the property's ownership history, identify certain title matters, coordinate settlement and prepare for the transfer of ownership.
If you're buying a home in Northern Utah or anywhere along the Wasatch Front, don't be afraid to ask questions when the title documents arrive.
Buying a home isn't just about finding a property you love.
It's also about making sure the ownership side of the transaction is ready for you to call it yours.
Recent Posts